 HYGO News
Jean-Pierre on Sparing Community Banks From the SVB Fee: 'Not Going to Go Into Specifics' (March 30, 2023)
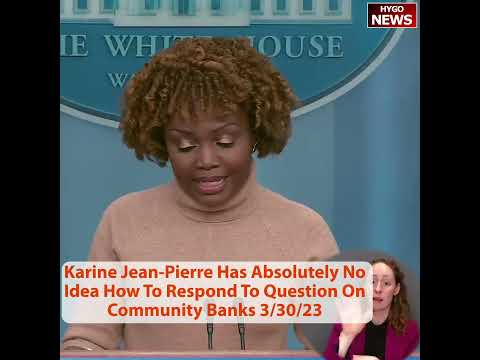
After Silicon Valley Bank and Signature Bank failed in March 2023, the Treasury Department, the Federal Reserve and the Federal Deposit Insurance Corporation protected all of their depositors and said that “any losses to the Deposit Insurance Fund to support uninsured depositors will be recovered by a special assessment on banks, as required by law” [2]. That raised a question that community bankers and senators from rural states quickly asked: would small banks pay to cover losses at big ones? At the White House briefing on March 30, a reporter asked Press Secretary Karine Jean-Pierre why the administration wanted the FDIC to spare community banks. This short clip shows her answer. Quotes are from the official transcript published by the American Presidency Project [1].
Key Moments
”Why not broaden the base?”
“I wanted to ask why the Biden administration wants the FDIC to spare community banks from the special assessment to cover, you know, the insuring — insurance deposits for Silicon Valley and Signature Banks,” the reporter said. “I mean, the default is that all banks pay. Why not broaden the base?” “So I just want to — are you asking about a particular bank in — a particular bank here?” Jean-Pierre asked. The reporter clarified: “the Biden administration earlier was talking about the FDIC sparing community banks from the special assessment. … The FDIC does have some discretion, I understand. But I — I wanted to understand why is — why is the administration encouraging that” [1].
”The DIF has more than enough”
“So, I’ll say this: Look, the D- — the DIF — the DIF has more than enough to cover — right? — any — any Silicon Valley Bank and Signature Bank deposits that cannot be paid using funds from the banks or the sale of their assets,” Jean-Pierre said. “And the FDIC has said any losses that the DIF will be — will be recovered by special assessment on the banks, not the taxpayers. We think it’s important to make sure that these community banks, these regional banks, are also put in a strong place, in a resil- — are also resilient as well” [1].
”I’m not going to go into specifics”
“And so I’m going to leave it there. I’m not going to go into specifics onto what the FDIC is doing. That is something for them to make that decision,” she said. “As you know, DIF is an important fund — insurance fund that the big banks pay into. But I’m not going to get into specifics on — to their — to their process” [1].
Background: The Fund and the Fee
The Deposit Insurance Fund is the pool the FDIC uses to protect insured depositors when banks fail. It held $128.2 billion on December 31, 2022, according to the FDIC [3]. Two weeks before Jean-Pierre’s answer, Sen. James Lankford of Oklahoma had pressed Treasury Secretary Janet Yellen on the same question, warning that community banks in his state would end up paying a special assessment to make large depositors whole; Yellen said then that the rules were “up to the FDIC to determine” (see our article on that hearing). On March 21, Yellen told the American Bankers Association that “similar actions could be warranted if smaller institutions suffer deposit runs that pose the risk of contagion” [5].
Fact Check
- “The DIF has more than enough to cover.” Accurate. Against the fund’s $128.2 billion balance [3], the FDIC later estimated that about $16.3 billion of the cost of the two failures was attributable to protecting uninsured depositors [4].
- “Recovered by special assessment on the banks, not the taxpayers.” Accurate as a description of the law and the agencies’ announcement [2][4]. Critics, including Lankford, argued that banks pass such costs on to customers; “every Oklahoman will pay higher fees in their community banks,” he told Yellen [8].
- “DIF is an important fund … that the big banks pay into.” Incomplete. According to the FDIC, the fund’s money comes from “assessments (insurance premiums) that FDIC-insured institutions pay” and from interest on Treasury securities; that includes small banks, not only the largest ones [7]. The question was who would pay the special assessment on top of that.
- Why spare community banks? She did not give the administration’s reasoning beyond saying community and regional banks should be “resilient,” and referred the specifics to the FDIC [1].
What Happened Next
- The final rule: On November 16, 2023, the FDIC adopted a final rule estimating that 114 banking organizations would pay the special assessment and that “no banking organizations with total assets under $5 billion will pay the special assessment” [4]. Banks the size of community banks were spared.
- Another failure: On May 1, 2023, regulators closed First Republic Bank in San Francisco, and JPMorgan Chase agreed to assume all of its deposits and substantially all of its assets [6].
Sources
- The American Presidency Project: Press Briefing by Press Secretary Karine Jean-Pierre (March 30, 2023)
- U.S. Department of the Treasury: Joint statement by the Department of the Treasury, Federal Reserve, and FDIC (March 12, 2023)
- FDIC: FDIC-Insured Institutions Reported Net Income of $68.4 Billion in Fourth Quarter 2022 (February 28, 2023)
- FDIC: FDIC Board of Directors issues a final rule on special assessment pursuant to systemic risk determination (November 16, 2023)
- U.S. Department of the Treasury: Remarks by Secretary Janet L. Yellen at the American Bankers Association’s Washington DC Summit (March 21, 2023)
- FDIC: JPMorgan Chase Bank, National Association, Columbus, Ohio assumes all the deposits of First Republic Bank, San Francisco, California (May 1, 2023)
- FDIC: Understanding Deposit Insurance
- GovInfo: Senate Hearing 118-429, The President’s Fiscal Year 2024 Budget with Treasury Secretary Janet L. Yellen (March 16, 2023)